Three out of four US consumers now choose digital banking over branches. Yet fewer than a third trust their neobank to hold their money. This is not a marketing issue, and better design will not solve it.
Adoption Has Outrun Confidence
Digital-first banking is now the default for most US consumers. A 2026 survey puts adoption at 76 percent, with digital-only providers capturing more net interest income globally. But usage and confidence have diverged. Trust remains highest for regional banks and credit unions at 67 percent, while neobanks lag at 30 percent. In Europe, nearly half of consumers hold a digital-only account, but a third still see neobanks as less secure than traditional banks.
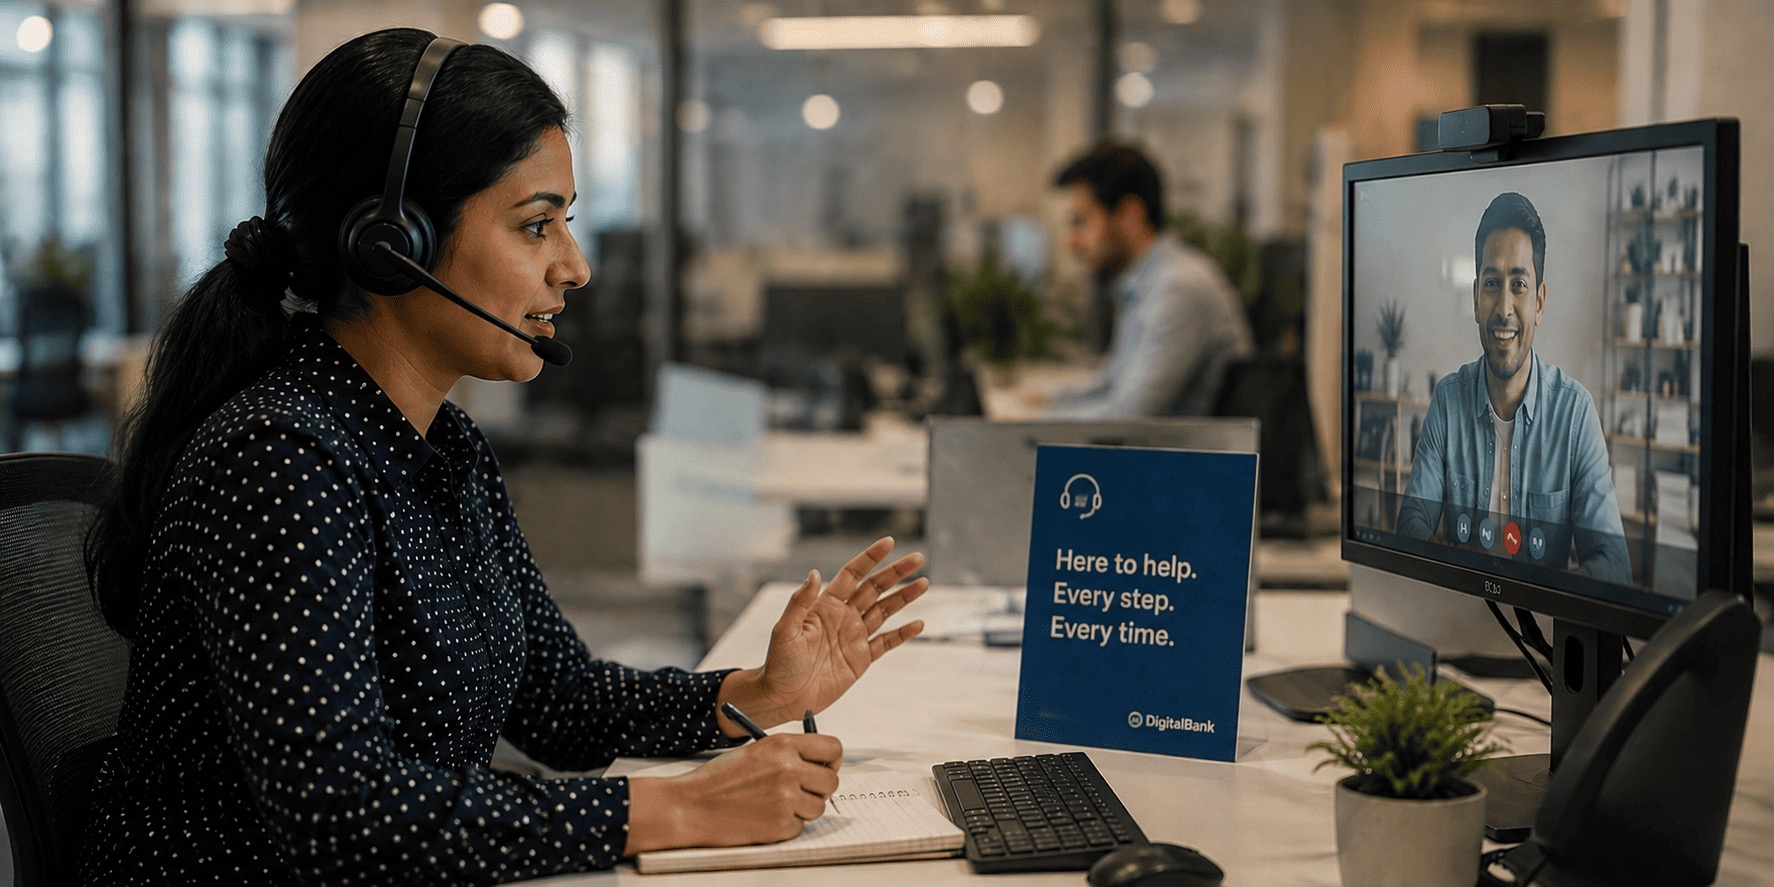
This is not an image problem. A 2026 satisfaction study found online-only banks outperforming neobanks on checking-account satisfaction, with the gap driven by operational failures: fraud issues and poor access to support when problems arise. Institutions are not losing trust because of outdated interfaces. They are losing it because customers cannot reach anyone when their money is at risk.
Personalization Is Not the Same as Reliability
Digital banking has spent years optimizing for personalization. Recent research shows providers are building tailored digital experiences, but still struggle with frequent customer problems and inadequate support. The industry has focused on making apps feel personal, not on resolving issues when they occur.
The difference is not subtle. Executives focused on feature parity—budgeting tools, predictive savings, AI-driven categorization—are competing on what consumers already expect. What actually drives retention is how the institution responds when something breaks: a disputed charge unresolved for weeks, a locked account with no support, a fraud alert with no explanation. Many neobanks rely on fragmented third-party vendors, leaving them exposed at the moments that matter most.
What the Institutions Getting It Right Are Actually Doing
Digital banks that outperform on trust do so through disciplined operational investment: support channels that work under pressure, clear communication about deposit location and insurance, and fraud resolution fast enough that customers are not left assuming their money is gone. Even the fastest-growing neobanks face structural challenges on trust. The ones making progress treat support infrastructure as a core product investment, not a cost to cut before an IPO.
Demographics matter. Digital-first banking is not just for early adopters. Gen Z is nearly twice as likely as average to use a digital-first bank as their primary institution, yet a significant share in the UK still plan to use branches—the highest of any generation. Confidence is not generational. It is built transaction by transaction, complaint by complaint.
The Strategic Takeaway
For bank and fintech leadership, the lesson is straightforward but rarely celebrated. Closing the trust gap in digital banking will not come from new AI features. It will require capital-intensive decisions: staffing support functions, investing in fraud detection and resolution speed, and being transparent about regulatory and custodial structures—especially in a market still dealing with the fallout from high-profile banking-as-a-service failures.
The digital banks that win over time are not those with the most features. They are the ones customers can reach at 2 a.m. when a card is declined. This is a lower bar than most product roadmaps admit, and a harder one to clear consistently.
Most institutions still treat adoption as a proxy for trust. The evidence suggests that gap is not closing on its own.